AI Bubble Fears Grow as Billionaires Sell Billions in Tech Stocks
Billionaires are selling AI-linked shares as hedge funds retreat from technology stocks and concerns grow over massive infrastructure spending, rising debt and whether the artificial intelligence boom can deliver the profits investors expect.
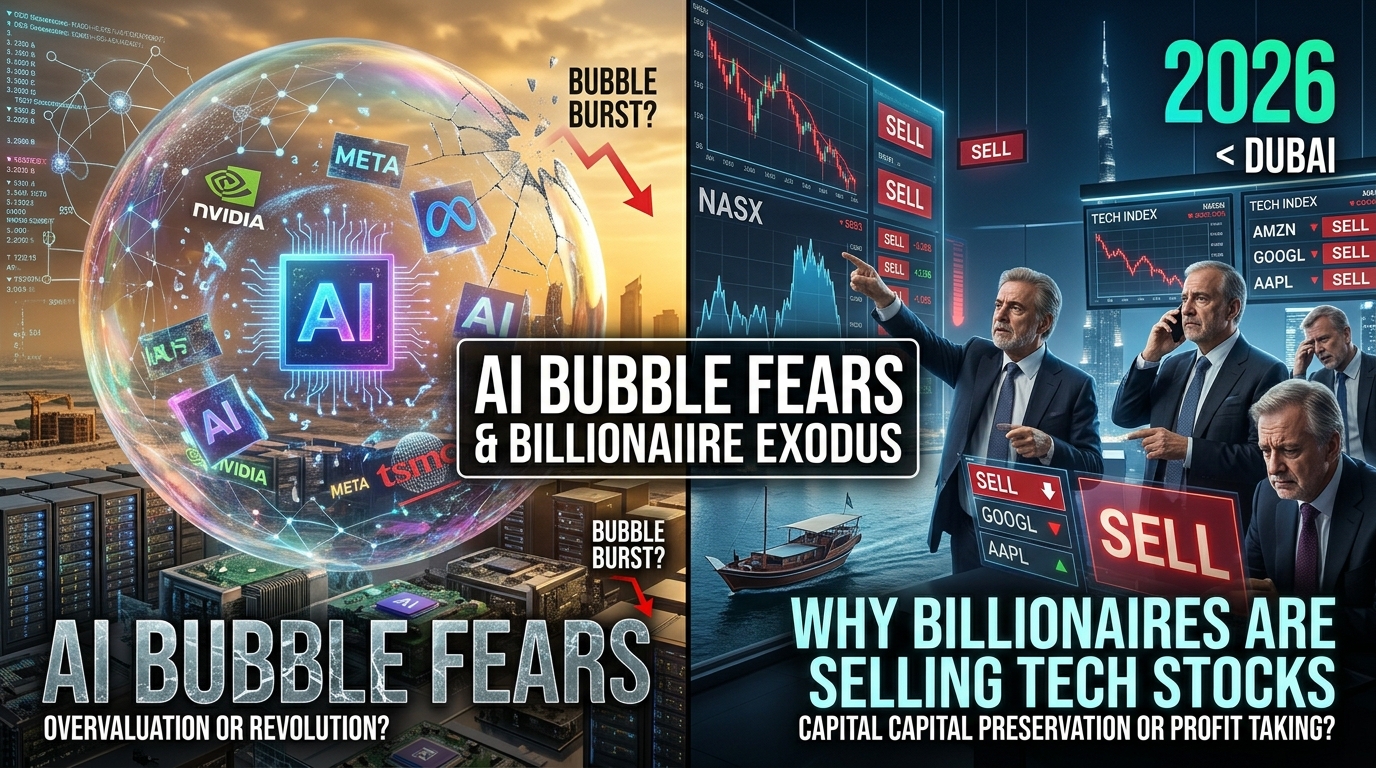
The artificial intelligence revolution is entering a more complicated financial phase. After years of extraordinary stock market gains, some of the people and institutions that benefited most from the technology boom are reducing their exposure to technology stocks. At the same time, the world's largest technology companies are committing hundreds of billions of dollars to artificial intelligence infrastructure.
The growing tension is difficult to ignore. Demand for AI services is expanding, cloud businesses are reporting strong growth, and companies continue to race to develop more powerful models. Yet the financial commitments required to sustain that expansion are becoming enormous.
The central question is no longer whether artificial intelligence will transform the economy. It is whether the companies investing so heavily in it can generate enough revenue and profit to justify the cost.
Why Are Billionaires Selling AI Stocks?
Some of the most prominent technology investors and executives have been selling shares in companies connected to the artificial intelligence boom.
Bloomberg reported in October that several high-profile insiders, including Nvidia director Mark Stevens, Arista Networks chief executive Jayshree Ullal and Amazon founder Jeff Bezos, were among the notable sellers during the third quarter of 2026.
These transactions have attracted attention because they involve people with close knowledge of the companies and industries driving the AI expansion. However, insider selling does not automatically mean executives expect a market crash.
Executives sell shares for several reasons, including diversification, personal liquidity, tax planning and prearranged trading programmes. A sale should therefore not be interpreted as proof that an insider has lost confidence in a company's future.
There is also an important distinction between insider transactions and institutional investors reducing their exposure. Hedge funds may sell technology stocks because of valuation concerns, portfolio rebalancing or expectations that other sectors will perform better.
Nevertheless, when large insider sales coincide with institutional selling and growing concerns about the cost of AI infrastructure, investors naturally begin questioning whether the market has become too optimistic.
The October 2026 Sell-Off Exposed the Industry's Financial Vulnerability
The technology sector experienced a significant correction at the end of October, revealing how sensitive investors have become to the financial demands of the AI industry.
On October 30, the Nasdaq Composite fell approximately 2.9%, leaving it around 7.8% below its October 6 closing record. Intel suffered a particularly sharp decline, falling 28.6%, while Nvidia dropped 4.2% and AMD lost 10.9%.
The sell-off reflected more than ordinary market volatility. Disappointing corporate results and concerns about the enormous sums being committed to artificial intelligence infrastructure contributed to a reassessment of technology valuations.
For years, investors rewarded companies for announcing ambitious AI investment plans. Increasingly, however, markets want evidence that those investments will produce sustainable earnings.
This represents an important change in the market's expectations. Spending more money on AI is no longer automatically viewed as a competitive advantage. Companies must demonstrate that the infrastructure they are building can generate sufficient returns.
The AI Boom Began With ChatGPT but Became an Infrastructure Race
The current investment cycle accelerated after OpenAI introduced ChatGPT to the public in November 2022. The technology demonstrated that generative AI could reach ordinary consumers and become a commercially valuable product.
Microsoft expanded its relationship with OpenAI, Google accelerated its own AI development, Amazon strengthened its cloud-based AI services, and Meta increased its investment in artificial intelligence research and infrastructure.
Nvidia became one of the biggest beneficiaries because its graphics processing units are essential for training and running many advanced AI systems.
But the AI revolution requires much more than software. It depends on semiconductor manufacturing, data centres, electricity, cooling systems, high-speed networks and enormous computing capacity.
This has transformed AI development into an infrastructure race. Technology companies are competing not only to build the most capable models but also to secure the physical resources required to operate them.
The problem is that infrastructure must often be financed years before its full commercial potential becomes clear. Companies are committing enormous amounts of capital today in anticipation of future demand.
That creates a financial risk: if the growth in AI revenue fails to match expectations, some of the infrastructure being built could become less profitable than investors currently assume.
Big Tech's AI Spending Is Becoming a Financial Test
The financial results of the largest technology companies demonstrate both the opportunity and the challenge.
Amazon reported that its cloud computing division, Amazon Web Services, generated approximately $46 billion in third-quarter revenue, representing year-over-year growth of 39.3%. AWS operating income reached $17.8 billion.
These figures demonstrate that demand for cloud computing and AI-related infrastructure is substantial. However, Amazon's investment programme is also becoming increasingly expensive.
The company reported a trailing 12-month free cash flow outflow of $42.4 billion, compared with positive free cash flow during the equivalent previous period. Amazon also indicated that its capital expenditure for 2026 could reach approximately $220 billion.
An important distinction is necessary: negative free cash flow does not mean Amazon is reporting an operating loss. It means the company's cash spending, particularly on investment, has exceeded the cash generated after accounting for capital expenditure.
Alphabet's results offer another example of the commercial opportunity. The company reported third-quarter revenue of approximately $127.6 billion, up 25% year over year. Google Cloud revenue reached $30.7 billion, representing growth of 103%.
These figures suggest that AI is already contributing to real commercial activity. Businesses are purchasing cloud services, integrating AI tools and increasing their demand for computing capacity.
But strong revenue growth does not eliminate the investment risk. The question is how much capital companies must spend to maintain that growth and how quickly the investment will translate into durable profits.
Meta's $97.5 Billion Fundraising Raises Questions About AI Financing
One of the most striking developments in the AI investment race came from Meta.
In October, Reuters reported that Meta was preparing an equity fundraising package worth approximately $97.5 billion. The proposed structure included $25 billion in common stock, $12.5 billion in convertible preferred securities and a separate share-sale programme that could raise up to $60 billion.
The fundraising attracted further attention after Nvidia and AMD announced investments of approximately $3 billion and $1 billion, respectively, connected to Meta's equity offering.
The scale of the financing reflects the extraordinary resources required to compete in the AI industry. Meta is investing heavily in data centres, computing infrastructure and the development of advanced AI systems.
Its financial results also illustrate the pressure involved. Meta reported third-quarter revenue of approximately $64.6 billion, up 26% year over year. However, its costs and expenses increased substantially, while capital expenditure reached approximately $34.9 billion.
The company also reported negative free cash flow of around $2.1 billion for the quarter.
Meta's results require careful interpretation. Its reported expense increase included a significant legal settlement charge, meaning the entire increase should not be attributed to AI investment.
Nevertheless, the broader financial picture is clear: the company is spending heavily to secure a position in a market whose long-term commercial structure is still developing.
The Circular AI Economy: Are Technology Companies Financing Their Own Customers?
One of the most important questions surrounding the AI boom concerns the increasingly interconnected financial relationships between technology companies.
Nvidia supplies chips used by cloud providers and AI developers. Cloud companies provide computing capacity to AI businesses. Those AI businesses use the infrastructure to develop products and services, while technology investors and strategic partners provide capital to companies across the ecosystem.
In some cases, companies that benefit from the growth of AI also invest in businesses that purchase their technology or use their infrastructure.
This creates a complicated commercial relationship. A company may benefit not only from selling products but also from investments and partnerships that help expand demand across the industry.
Such arrangements are not automatically improper. Strategic investments, commercial partnerships and long-term supply agreements are common in the technology sector.
However, they make it more difficult for investors to assess the quality of demand. If revenue growth depends heavily on a relatively small group of interconnected companies, the market must examine whether the demand is ultimately supported by independent customers and sustainable economic activity.
The concern is not that every transaction is artificial. It is that the financial relationships within the AI ecosystem could amplify the consequences if investment enthusiasm weakens.
Could AI Debt Create a Wider Financial Problem?
The AI infrastructure boom is increasingly connected to borrowing.
Building data centres requires substantial upfront capital. Companies must acquire land, construct facilities, purchase specialised equipment, secure electricity supplies and establish networks capable of handling enormous computing workloads.
Some technology companies can finance these investments through existing cash flows and balance sheets. Others rely more heavily on corporate bonds, private credit and infrastructure financing.
This creates a potential vulnerability.
If AI demand continues growing rapidly, borrowing to build infrastructure may produce attractive returns. But if demand slows, computing prices decline or facilities remain underused, companies could struggle to generate enough revenue to cover their financing costs.
The Federal Reserve Bank of Kansas City has examined the longer-term financial risks associated with the AI build-out, including borrowing, asset valuations and the potential consequences of a large infrastructure investment cycle.
The concern extends beyond individual technology companies. Banks, private credit funds, bond investors and infrastructure lenders may all have exposure to the same underlying assumptions about future AI demand.
A correction in technology stocks would not automatically trigger a financial crisis. However, a deeper downturn could become more serious if heavily indebted companies and infrastructure investors discover that the assets they financed are not generating the expected returns.
Is the AI Boom Repeating the Dot-Com Bubble?
Comparisons with the dot-com bubble of the late 1990s are becoming increasingly common.
During that period, investors poured money into internet companies, many of which had limited revenue and no sustainable business models. The belief that the internet would transform the economy encouraged valuations that were disconnected from the financial performance of individual companies.
The eventual collapse destroyed enormous amounts of market value. Yet the internet itself continued to expand and became central to the global economy.
The AI boom shares some similarities. Investors are placing enormous expectations on a technology whose commercial applications are still evolving. Companies are committing capital ahead of proven returns, while valuations in parts of the market reflect expectations of years of future growth.
There are also important differences.
Today's AI expansion is being driven by established technology companies with substantial existing businesses, recurring revenue and significant cash-generating operations. Microsoft, Amazon, Alphabet and Meta are not simply speculative start-ups.
Their cloud businesses, advertising platforms, software products and other services already generate significant revenue.
That does not make their AI investments risk-free. Even financially strong companies can overpay for infrastructure, underestimate operating costs or invest in capacity that eventually becomes less valuable.
The most important lesson from the dot-com crash is that a technology can transform the world while many of the investments made during its early expansion still lose money.
The Depreciation Question: Are AI Infrastructure Assets Becoming Obsolete Too Quickly?
Another important issue concerns the useful life of AI infrastructure.
Data centres, servers and specialised computing equipment are expensive assets. Companies generally spread the cost of these assets over several years through depreciation.
The assumptions used to calculate depreciation can have a meaningful effect on reported profits.
If a company expects servers to remain productive for a long period, it spreads their cost over more years. That can reduce annual depreciation expenses and increase reported operating profits in the short term.
However, AI hardware is developing rapidly. New generations of chips can deliver substantial improvements in performance and efficiency, potentially making older equipment less competitive.
This does not mean older hardware immediately becomes worthless. Existing equipment can continue operating, serve less demanding workloads or be used in different applications.
The important question is whether the useful lives assumed in financial statements accurately reflect the economic value companies can extract from their infrastructure.
If equipment becomes commercially outdated faster than expected, companies may eventually face higher depreciation expenses or impairment charges.
For investors, the issue is not simply how much companies spend building data centres. It is how long those investments remain productive and how much revenue they generate before being replaced.
What Happens to Africa if the AI Investment Boom Slows?
The consequences of an AI correction would extend beyond Wall Street and Silicon Valley.
African economies are increasingly interested in artificial intelligence as a way to improve financial services, healthcare, education, agriculture and public administration. However, much of the infrastructure required to support these applications remains concentrated outside the continent.
African businesses and governments often depend on foreign cloud providers, international data centres and externally developed AI services.
A major slowdown in AI investment could create both opportunities and risks.
If infrastructure investment contracts, some planned data centre projects could be delayed or cancelled. This could slow the expansion of local computing capacity and limit access to advanced services.
On the other hand, a correction could reduce the cost of computing infrastructure and make specialised hardware more affordable. Lower prices could help African developers, universities and smaller businesses access technology that is currently expensive.
The long-term outcome will depend on whether African countries use the period to strengthen electricity supply, internet connectivity, technical education and local digital infrastructure.
The AI investment cycle therefore matters to Africa even if most of the financial speculation is taking place in the United States.
The continent's challenge is to avoid becoming only a consumer of foreign AI technology while missing the opportunity to build businesses and infrastructure around it.
What Happens If the AI Bubble Bursts?
There are several possible outcomes for the AI industry.
The first is a sustainable expansion. AI adoption continues growing, businesses find profitable applications, and the revenue generated by AI services eventually justifies much of the infrastructure spending. In this scenario, current market volatility becomes a temporary adjustment.
The second is a correction without the collapse of the technology. Investors become more selective, valuations decline and companies reduce spending on projects that cannot demonstrate commercial value. AI development continues, but the financial rewards become more concentrated among businesses with strong products and efficient operations.
The third is a deeper investment crisis. AI demand grows more slowly than expected, infrastructure becomes underutilised and heavily indebted companies struggle to repay their obligations. Technology stocks fall further, lenders reassess their exposure and investment projects are cancelled.
The third scenario would be the most damaging, but it is not inevitable. Strong cloud growth and continued demand for AI services demonstrate that the industry has genuine commercial foundations.
The uncertainty lies in whether the financial commitments made today are proportionate to the revenue opportunities that will emerge tomorrow.
Five Indicators That Will Determine Whether the AI Boom Is Sustainable
Investors should pay attention to several indicators over the coming quarters.
1. Nvidia's earnings and chip demand: Nvidia's financial performance provides an important indication of demand for AI computing infrastructure. A slowdown in orders or weakening margins could signal that customers are becoming more cautious.
2. Cloud revenue growth: The performance of AWS, Google Cloud and Microsoft Azure will help demonstrate whether businesses are continuing to purchase AI-related computing capacity.
3. Free cash flow: Revenue growth is important, but investors must also examine how much cash companies retain after financing their investment programmes.
4. Corporate debt and private credit exposure: The expansion of AI infrastructure financing means that borrowing costs, repayment capacity and asset valuations deserve greater scrutiny.
5. Actual AI monetisation: The ultimate test is whether companies can turn AI adoption into recurring revenue and sustainable profits rather than relying primarily on expectations of future growth.
These indicators will help distinguish a commercially sustainable technological expansion from an investment cycle driven mainly by optimism.
The AI Revolution May Survive Even If the AI Investment Bubble Bursts
The growing concerns surrounding AI stocks should not be confused with a rejection of artificial intelligence itself.
The technology is already changing how companies operate, how software is developed and how people access information. Businesses are finding practical applications in customer service, research, healthcare, finance and industrial operations.
Those developments are unlikely to disappear simply because investors become more cautious.
But technological importance does not guarantee that every company investing in the industry will succeed. Nor does it mean that today's market valuations are justified.
The internet transformed the global economy after the dot-com crash, but many companies that attracted enormous investment during the original boom never recovered. The companies that eventually dominated the digital economy were not necessarily the ones investors expected to win in the beginning.
Artificial intelligence could follow a similar path.
The companies building today's infrastructure may become some of the most important businesses of the next decade. Others may discover that they invested too much, borrowed too heavily or underestimated how quickly technology would change.
The central risk is therefore not that artificial intelligence will fail to transform the world. It is that financial markets may have priced in too much of that future, too early.
For investors, the next phase of the AI revolution will be less about promises and more about proof: proof that demand is sustainable, infrastructure is productive, debt is manageable and enormous investment can ultimately generate lasting profits.