The Invisible Divide: How Old Money and Exclusionary Zoning Broke Connecticut’s Economy
Behind Connecticut’s picturesque suburbs and elite hedge funds lies the second most unequal economy in America. Through decades of industrial decline, preferential tax shifts, and restrictive single-family zoning, the state has built an invisible wall that isolates immense fortunes from struggling cities—leaving public services fragile and upward mobility locked by zip code.
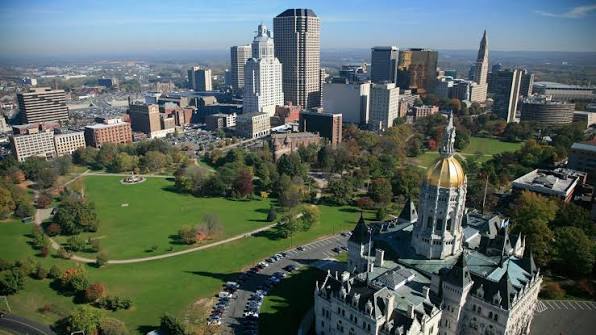
Nestled between New York City and Boston, Connecticut fits the quintessential image of quiet American prosperity: leafy lanes, colonial architecture, coastal private beaches, and historic stone walls. Towns like Greenwich and Westport are cultural shorthand for dynastic wealth and blue-chip hedge funds, and the state consistently ranks near the top nationwide in millionaire households per capita.
Beneath that placid surface, however, sits one of the most fractured economic landscapes in the United States.
By standard metrics of inequality, Connecticut is the second most unequal state in America, trailing only New York. But while New York’s gap is largely driven by a single global financial capital towering over a rural upstate, Connecticut has no sprawling metropolis. Instead, some of the wealthiest enclaves on Earth sit directly adjacent to deeply impoverished, under-resourced cities—separated not by geography, but by an invisible regulatory wall.
The Illusion of Universal Affluence
Economists measure inequality using the Gini coefficient, a scale from 0 (perfect equality) to 1 (a single person captures all income).
The global standard: Most developed economies sit between 0.25 and 0.40.
The U.S. average: Roughly 0.42.
Connecticut: Approximately 0.50—a figure closer to developing nations like Brazil than Western Europe.
This disparity stems primarily from extreme concentration at the top. The top 1% of earners in Connecticut take home approximately 28% of all personal income generated in the state, earning roughly 37 times more than the bottom 99%. In the metro area spanning Bridgeport and Stamford, that ratio balloons to an astounding 62 to 1.
Bridgeport–Stamford Income Comparison
────────────────────────────────────────────────────────────────
Top 1% Average Annual Income:    $6,300,000  (████████████████)
Bottom 99% Average Annual Income:  $101,000  (▎)
────────────────────────────────────────────────────────────────
On paper, Connecticut’s official poverty rate appears modest. But the federal poverty guideline—around $33,000 a year for a family of four—reflects little of local economic reality. According to United Way cost-of-living data, a family of four in Connecticut requires roughly $116,000 annually just to meet essential needs like housing, food, transportation, and healthcare. When measured against what life in the state actually costs, nearly 4 in 10 households fall short.
The Great Swap: From Manufacturing Hub to Financial Haven
Connecticut was not always an economy of extreme divides. In the late 19th century, Hartford was considered the wealthiest city in America per capita. It was an industrial powerhouse, home to titan insurers like Aetna and The Hartford, Colt’s manufacturing plants, and extensive rail networks. Surrounding towns flourished in tandem: Danbury was the world capital of hatmaking, Waterbury dominated American brass production, and Bridgeport earned fame as the "Arsenal of Democracy."
Over the latter half of the 20th century, that industrial base steadily eroded. Automation reduced factory headcounts, while manufacturing operations moved south, west, or overseas in search of lower labor and operating costs.
As factories emptied out, capital and affluent white families moved outward into suburban bedroom communities. Redlining and racially restrictive covenants barred non-white families from following, locking minority residents into urban centers whose commercial tax bases were rapidly evaporating.
1910 vs. Modern Home Value Inversion
────────────────────────────────────────────────────────
1910:  Hartford Average Home Value:  ~$5,000  (Urban Core)
       Avon Average Home Value:      ~$1,200  (Rural/Suburban)

Today: Avon homes sell for roughly 3x the value of Hartford homes.
────────────────────────────────────────────────────────
Meanwhile, Fairfield County—positioned just an hour's commute from Midtown Manhattan—underwent a transformation of its own. Long a weekend haven for old-money families like the Rockefellers, the area became a magnet for hedge funds and private equity firms in the 1990s and early 2000s.
Tax policy accelerated the shift:
The Pre-1991 Tax Haven: Prior to 1991, Connecticut levied zero tax on earned wages, drawing corporate headquarters out of high-tax Manhattan.
The 1991 Restructure: The state introduced a general income tax but simultaneously slashed the tax rate on investment income down to 4.5%—a custom-tailored incentive for asset managers.
The Cluster Effect: Mega-funds like Bridgewater Associates took root in small coastal towns like Westport.
Connecticut traded an economy of manufacturing jobs that paid decent, widespread wages to many for a financial services industry that paid astronomical sums to very few.
The Real Mechanism: Town Borders and Zoning Laws
Wealth disparities exist across the country, but Connecticut’s municipal structure ensures that wealth never cross-pollinates.
In 1960, Connecticut abolished county government entirely. The state was divided into 169 autonomous municipalities, each with absolute authority over its own zoning, land use, schooling, and emergency services.
Because towns rely on local property taxes for roughly 60% of their revenue (nearly double the national average), this fragmentation produces an aggressive feedback loop:
    Wealthy Enclave                       Struggling City
  ────────────────────                  ────────────────────
 High Property Values                  Low Property Values
          │                                     │
          ▼                                     ▼
 Enormous Tax Revenue                  Depleted Tax Revenue
          │                                     │
          ▼                                     ▼
 Superior Public Schools               Underfunded Schools &
 & Pristine Services                    High Social Demands
          │                                     │
          ▼                                     ▼
Attracts Wealthy Buyers;              Wealth Departs;
Values Appreciate Further             Tax Base Shrinks Further
To preserve this advantage, suburban towns deploy exclusionary zoning. Approximately 91% of Connecticut's residential land is zoned exclusively for single-family homes. Only 2% allows multi-family housing of four or more units by right. In several municipalities, zoning mandates several acres of land just to build a single home, and some have approved zero multi-family units in over two decades.
Even the state's flagship affordable housing law—Statute 8-30g, enacted in 1989 to allow developers to bypass local zoning boards in towns where less than 10% of housing stock is deemed affordable—has barely moved the needle. Over thirty years later, fewer than 30 of Connecticut's 169 towns have met the 10% threshold.
No physical walls are necessary. When a town mandates large-lot single-family homes, low- and middle-income families are automatically priced out of both the neighborhood and its school district.
A Fragile Foundation
Connecticut does not face the turbulent street-level displacement seen in rapidly gentrifying cities like Miami or San Francisco. The money remains walled off in its own preserves, leaving working-class residents confined to disinvested post-industrial cores.
Yet this design carries profound long-term risks:
1. Educational Apartheid
More than half of Connecticut’s non-white residents live in just 10 of the state’s 169 towns, while roughly 30 suburban towns remain over 90% white. In Greenwich, the district spends upwards of $27,800 per student, and nearly 80% of third-graders meet state reading benchmarks. Down the road in Bridgeport, where over 90% of students are classified as high-need, spending drops to roughly $18,900 per student, and only one in six third-graders reads at grade level.
2. A Dangerous Fiscal Precipice
Connecticut’s public finances rest on a hyper-concentrated base: just 1.1% of tax filers generate 40% of the state's entire personal income tax revenue.
Because ultra-wealthy residents are globally mobile, the departure of just a handful of marquee hedge fund managers to low-tax jurisdictions like Florida delivers a measurable shock to the state budget. Financial and insurance sector jobs in the state have contracted significantly over the past two decades, leaving public revenue vulnerable to the whims of a few dozen estates.
The Verdict
Connecticut is neither economically destitute nor visibly unstable. Its leafy suburbs remain among the most comfortable, well-resourced communities in the world.
Instead, it is economically trapped. The state relies on a handful of mobile billionaires to balance its books, while maintaining a zoning and municipal structure that systematically denies upward mobility to hundreds of thousands of its own citizens. Fixing the budget requires retaining capital; fixing the economy requires dismantling the regulatory walls that decide a child's future before they ever leave their zip code.
FAA ground stop: the air traffic network that failed is one the FAA said in August could no longer cope
 Essay