America's Social Security Tax Paradox: Why Millionaires Stop Paying in March While Workers Pay All Year
In 2027, an American earning $1 million annually will reach the Social Security payroll tax ceiling by March 12, while someone earning $60,000 will contribute throughout the year. Meanwhile, the average retired worker will receive an increase of just $75 a month. The contrast exposes a deeper debate about economic inequality, retirement security and who should finance America's social safety net.
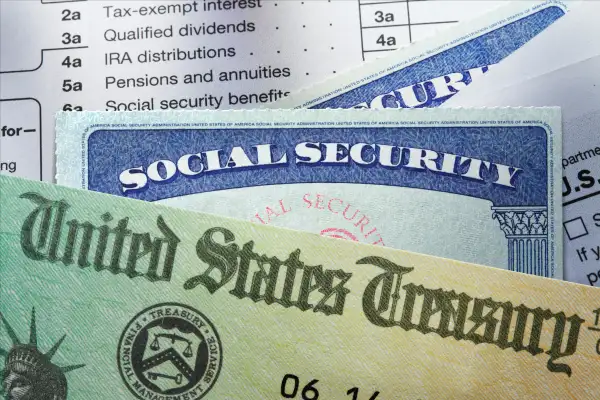
On March 12, 2027, an American earning $1 million a year will have paid the maximum amount of Social Security payroll tax required of an employee for that year.
Someone earning $60,000 will still be paying the tax on every remaining paycheck until December.
The difference is not the result of an accounting error or a special exemption negotiated by wealthy individuals. It is how America's Social Security tax system is designed. The federal government limits the amount of annual earnings subject to Social Security payroll taxation. Once a worker's income crosses that threshold, the Social Security portion of the payroll tax stops applying to additional earnings.
For 2027, that ceiling is $192,300.
The result is a striking contrast. A worker earning $60,000 contributes throughout the year, while someone earning $1 million reaches the maximum taxable income after earning less than one-fifth of their annual salary.
At the same time, millions of Americans relying on Social Security retirement benefits are preparing for a 3.6 percent cost-of-living adjustment in 2027. The Social Security Administration estimates that the average retired worker will receive approximately $75 more per month.
Taken together, these figures reveal a fundamental tension in America's retirement system: the programme is expected to support an ageing population, but the rules governing its financing limit how much of the highest incomes are subject to its principal payroll tax.
The question is increasingly difficult to avoid. Should Americans earning millions of dollars stop contributing to Social Security after reaching the annual earnings ceiling, even as the programme faces a long-term financing shortfall?
The March 12 deadline: How the Social Security tax ceiling works
Social Security is financed primarily through payroll taxes paid by employees and employers.
For 2027, employees pay 6.2 percent of their wages toward Social Security, while employers contribute an additional 6.2 percent. Together, the two sides contribute 12.4 percent of eligible earnings.
However, the tax does not apply to unlimited income.
The Social Security Administration has set the maximum taxable earnings for 2027 at $192,300, up from $184,500 in 2026. This means that an employee earning $192,300 or more will pay a maximum of $11,922.60 in Social Security payroll tax during the year.
The calculation is straightforward:
A worker earning $60,000 pays 6.2 percent of that income, contributing $3,720.
A worker earning $192,300 pays $11,922.60.
A worker earning $1 million also pays $11,922.60.
The difference is what happens to income above the threshold. Once the worker earning $1 million reaches $192,300 in annual wages, additional earnings are no longer subject to the 6.2 percent employee Social Security tax.
Assuming income is earned evenly throughout the year, someone making $1 million annually crosses the threshold around March 12. A person earning $500,000 reaches it around May 21, while someone earning $5 million reaches it in January.
For an employee earning $60,000, the ceiling is never reached. Social Security tax continues to apply to every dollar of eligible wages throughout the year.
This creates an important distinction between the amount of tax paid and the share of income subject to taxation.
The employee earning $60,000 contributes 6.2 percent of their entire salary. The employee earning $1 million contributes the same maximum dollar amount as someone earning approximately $192,300.
As a result, the effective Social Security tax rate on the millionaire's total salary is approximately 1.19 percent, compared with 6.2 percent for the worker earning $60,000.
The employer's contribution follows the same taxable earnings ceiling. Self-employed individuals generally pay both sides of the Social Security tax, meaning their combined rate is 12.4 percent on covered self-employment earnings up to the same limit.
It is important, however, not to confuse Social Security taxation with all payroll taxation. Medicare taxes operate under different rules. The standard 1.45 percent Medicare tax paid by employees applies to all covered wages, without the Social Security earnings ceiling. Higher-income workers may also face an additional Medicare tax.
The March deadline therefore marks the end of the employee's Social Security payroll tax obligation for the year, not the end of all federal payroll taxes.
Why the system has an earnings ceiling
The Social Security earnings cap is not an arbitrary annual decision by the government. It is built into the structure of the programme.
Social Security is an earned-benefit system. Workers contribute through payroll taxes during their careers, and their earnings records help determine the retirement benefits they eventually receive.
The maximum taxable earnings limit also generally limits the amount of annual earnings counted when calculating Social Security benefits.
The ceiling is adjusted annually using changes in the national average wage index. This is why the limit increases from $184,500 in 2026 to $192,300 in 2027.
The original logic of the system was to connect contributions and benefits. Workers contribute on covered earnings, and those contributions help finance benefits based on their lifetime earnings histories.
But that arrangement produces a structural inequality in the tax burden.
A person earning several million dollars does not contribute Social Security tax on every dollar earned. Someone with a modest salary, by contrast, pays the tax on nearly every dollar of wages.
Supporters of the existing structure argue that Social Security is not intended to operate as an unlimited tax on income. They also point out that the programme is designed around earned benefits rather than a purely redistributive model.
Critics argue that the earnings ceiling allows the highest-paid workers to contribute a smaller proportion of their total income than ordinary employees.
The disagreement is not simply about whether wealthy Americans should pay more. It concerns the fundamental design of a programme that combines social insurance, retirement savings principles and income redistribution.
The $75 retirement increase: Relief that may not feel like relief
The second figure in the 2027 Social Security announcement is equally important.
The Social Security Administration has announced a 3.6 percent cost-of-living adjustment for 2027. The increase will affect nearly 72 million Social Security beneficiaries, with payments rising beginning in January.
For the average retired worker, the monthly benefit is expected to increase from approximately $2,095 to $2,170.
That represents an additional $75 a month, or roughly $900 over a full year.
For a household relying heavily on Social Security, the increase can help cover essential expenses. But the adjustment should not be confused with a substantial improvement in living standards.
A cost-of-living adjustment is intended to help benefits keep pace with inflation. It is not necessarily designed to make retirees wealthier or restore purchasing power lost over previous years.
The adjustment is calculated using the Consumer Price Index for Urban Wage Earners and Clerical Workers, commonly known as CPI-W. The formula compares price changes during the third quarter of one year with the corresponding period in the previous year.
This method has attracted criticism because the spending patterns of older Americans can differ from those of working-age households.
Retirees may devote a larger share of their income to healthcare, prescription medication and housing-related expenses. If those costs rise faster than the index used to calculate the annual adjustment, the official increase may not fully reflect the financial pressure experienced by older households.
There is another complication: the $75 figure is an average increase in gross benefits. It does not mean every retiree will receive exactly $75 more, and deductions such as Medicare premiums can affect the amount ultimately received.
For some retirees, the adjustment may provide meaningful relief. For others, it may simply help cover a portion of rising expenses.
The deeper problem: Social Security faces a funding challenge
The debate over the earnings ceiling is becoming more consequential because Social Security faces a long-term financial imbalance.
The programme is funded through payroll contributions and other income, including interest earned on its trust fund reserves. But the financial pressure created by an ageing population and changing demographic patterns has made the relationship between incoming revenue and scheduled benefits increasingly difficult to sustain.
The 2026 Social Security Trustees Report projects that the Old-Age and Survivors Insurance trust fund, which finances retirement and survivors' benefits, will be depleted in the fourth quarter of 2032 under the trustees' intermediate assumptions.
At that point, continuing programme income would be sufficient to pay approximately 78 percent of scheduled benefits if Congress had not enacted changes.
The combined retirement and disability trust funds are projected to be depleted in the third quarter of 2034. Under that combined projection, continuing income would cover approximately 83 percent of scheduled benefits.
These dates do not mean Social Security will disappear. Payroll taxes would continue to be collected, and benefits would continue to be paid. The problem is that the income available under current law would not be sufficient to finance all scheduled payments once the reserves were depleted.
The distinction is important. Social Security is not facing a sudden shutdown, but it does face a financing gap that will eventually require legislative action.
Demographic change is a major part of the challenge. Americans are living longer, and the population is ageing. Meanwhile, lower birth rates and changes in the number of workers supporting each beneficiary affect the programme's financial foundation.
In simple terms, the relationship between the number of people paying into the system and the number receiving benefits is changing.
This is not a problem that can be solved simply by announcing a higher annual cost-of-living adjustment. The underlying financing structure must also be addressed.
Should America remove the Social Security earnings cap?
The March 12 figure has renewed attention on one of the most prominent proposals for reform: requiring high earners to pay Social Security tax on more of their income.
The argument for expanding the taxable earnings base is relatively straightforward.
If someone earning $1 million currently pays Social Security tax on only the first $192,300, applying the tax to a greater share of that salary would generate additional revenue.
Supporters argue that the current system places a relatively heavier tax burden on lower- and middle-income workers, whose entire wages are generally subject to the Social Security tax.
They believe high earners should contribute more toward the programme, particularly when its long-term financing is under pressure.
Several reform proposals have explored different approaches. Some would apply Social Security payroll taxes to earnings above a new threshold, while others would gradually extend the tax to a much larger share of wages.
One proposal associated with Representative John Larson, the Social Security 2100 Act, has included additional taxation of high earnings. The Social Security Expansion Act, introduced by Senator Bernie Sanders and Senator Elizabeth Warren, has also proposed changes that would increase contributions from higher-income Americans.
These proposals differ in their details, including how additional contributions would affect future benefits. They should not be mistaken for enacted law.
There are also important arguments against simply removing the ceiling.
First, Social Security is structured around a relationship between contributions and benefits. If high earners are required to pay tax on substantially more income, policymakers must decide whether those additional contributions should generate higher future benefits or whether they should primarily strengthen programme finances.
Second, increasing payroll taxation can affect the cost of employing workers. Employers already contribute 6.2 percent on covered wages. Expanding the taxable earnings base would increase their tax obligations for highly paid employees as well.
Third, the earnings cap is only one part of the programme's long-term financial challenge. Changing it may improve revenue, but the final effect depends on the details of the reform, economic behaviour, benefit calculations and other policy decisions.
The real debate is therefore not simply whether millionaires should pay more. It is how much additional revenue the programme needs, who should provide it and what benefits should be attached to those contributions.
The alternatives: Higher taxes, later retirement or reduced benefits?
Removing or raising the earnings ceiling is not the only option available to policymakers.
Congress could increase the payroll tax rate, gradually raise the retirement age, modify benefit calculations, change the cost-of-living adjustment formula or combine several reforms.
Each option carries political and economic consequences.
Increasing the payroll tax rate would spread additional costs across covered workers and employers. Although a relatively small increase might generate significant revenue across the workforce, it would also reduce take-home pay and increase employment costs.
Raising the full retirement age would reduce lifetime benefits for many people who claim at the new eligibility thresholds. Supporters may argue that longer life expectancy justifies a later retirement age. Critics counter that people in physically demanding occupations and those with shorter life expectancies could be disproportionately affected.
Changing benefit calculations could reduce future payments, particularly for higher-income retirees. But such changes would need to be designed carefully to avoid increasing poverty among older Americans.
Removing or expanding the earnings cap would focus more of the additional contribution on higher earners, but it would raise questions about how those contributions translate into future benefits.
There is no painless solution. Every major reform involves a decision about who pays more, who receives less or how much financial pressure is transferred to future generations.
The longer Congress delays a decision, the narrower the time available for gradual changes.
Why this debate matters beyond millionaires and retirees
At first glance, the March 12 deadline may look like a technical detail in the American tax system. But it reveals a larger issue about the relationship between income, taxation and economic security.
For workers, Social Security is not simply another payroll deduction. It is a promise that contributions made during their working lives will help provide income in retirement, as well as protection for survivors and people with qualifying disabilities.
For retirees, the programme can be the foundation of their financial survival.
For businesses and employers, payroll taxes are part of the cost of employment.
And for policymakers, Social Security is one of the most politically sensitive parts of the federal budget because millions of Americans depend on it.
The challenge is that the programme must serve people with very different financial circumstances. Some retirees have substantial private savings, pensions and investment income. Others rely on Social Security for most of their monthly income.
The same is true of workers. A payroll tax that represents a manageable deduction for a high-income professional may be a much heavier burden for someone living paycheck to paycheck.
This is why the question of the earnings ceiling cannot be separated from the broader discussion about economic inequality.
The issue is not whether a person earning $1 million should be punished for being successful. It is whether the rules governing a national social insurance programme distribute the responsibility for financing it in a way that is sustainable and defensible.
The political test ahead
Social Security reform has repeatedly proved difficult in Washington because every proposed solution creates winners and losers.
Raising taxes on high earners can attract public support among those who believe the wealthy should contribute more. But it can also face opposition from business groups, taxpayers and lawmakers concerned about higher employment costs or changes to the programme's original design.
Raising the retirement age can be presented as a response to longer life expectancy, but it risks placing a disproportionate burden on people who cannot realistically work longer.
Reducing benefits can improve the programme's finances on paper, but it creates obvious political and social resistance among people who have planned their retirement around existing rules.
The difficulty is that Social Security reform is not merely an accounting exercise. It is a debate about the social contract between generations.
Workers today finance benefits for current retirees while expecting future workers to help support them when they retire. When that relationship becomes financially strained, policymakers must decide how the burden should be distributed.
The 2027 figures make that decision harder to ignore. An employee earning $1 million will reach the Social Security tax ceiling in March. A worker earning $60,000 will pay throughout the year. Meanwhile, the average retiree will receive an additional $75 a month, and the programme's retirement trust fund is projected to run short of reserves in 2032.
None of these figures alone proves that the Social Security system is unfair or beyond repair. But together they expose the questions that Congress has struggled to answer.
America's Social Security challenge is not simply about finding more money. It is about deciding who should contribute, who should be protected and whether the system can continue to deliver on its promises without placing an unsustainable burden on future generations.
FAA ground stop: the air traffic network that failed is one the FAA said in August could no longer cope
 Essay